When an insurance company or plan administrator denies your claim, it is rarely a decision about you. It is usually a policy — a coverage exclusion, a reviewer standard, a plan amendment, a fee arrangement — applied the same way to everyone in the plan. You experience it as one denial letter. It is actually a pattern.
That is what a class action is for. When the same conduct harms a group of employees, retirees, or beneficiaries, bringing one case on behalf of all of them is often the only realistic way to challenge it — because individually, the loss may be too small to litigate, and collectively, it is large enough that the plan had a financial reason to do it in the first place.
Kantor & Kantor has spent decades representing people whose benefits were wrongly denied. Our California ERISA attorneys handle individual claims every day, and when a denial turns out to be systemic, we have the experience and the resources to take it on as a class action. Call 866-318-5283 for a free case evaluation.
Denied benefits that hit your whole plan? Contact Kantor & Kantor, LLP online or call us at 866-318-5283 for a free case review.
When a Denied Benefit Is Bigger Than One Claim
Large insurers and plan administrators sometimes adopt practices whose individual impact is modest but whose aggregate effect is enormous. A slightly wrong actuarial assumption. An exclusion applied more aggressively than the plan language supports. A reviewer protocol that reaches the same conclusion nearly every time. Spread across thousands of participants, small unfairness becomes substantial profit.
The economics of that are deliberate. Most people will not hire a lawyer over a few thousand dollars, and the plan knows it. A class action reverses that math: it lets a group of people who were harmed the same way pursue the claim together, with one set of lawyers carrying the cost and the risk.
It also changes what a win looks like. An individual appeal gets one person their benefit. A class action can force the plan to stop the practice, which protects everyone still in it, including people who never knew they had a claim.
Do You Have a Class Action Case?
Three things generally have to be true. Not every unfair denial can be a class action, and an honest answer early saves everyone time.
A common issue, not just a common feeling. The people affected have to have been harmed by the same conduct — the same exclusion, the same amendment, the same reviewer policy — not simply by the same company. Two people denied by the same insurer for entirely different reasons do not share a claim.
A pattern that is provable. There has to be evidence the conduct was systemic: plan documents, internal guidelines, denial letters that repeat the same language, or a policy applied across a defined group. Much of this is not visible from the outside, which is why the first conversation is about what you have and what we would need to find.
A group approach that makes sense. Sometimes an individual claim is simply worth more to you than being one member of a class. We will tell you when that is the case. If your denial is genuinely individual, we handle those cases too, and we would rather bring you the right case than the bigger one.
If you are not sure which category you are in, that is a normal place to start. Call 866-318-5283 and we will tell you what we see.
Types of Benefits Class Actions We Handle
Our practice is employee benefits and insurance denials. That focus is what lets us recognize a systemic problem when it is still sitting in a single denial letter.
Retirement, Pension, and 401(k) Cases
ERISA was written to protect retirement benefits, and plan-wide retirement disputes remain among the most consequential class actions brought under it. These cases include breach of fiduciary duty by plan administrators — imprudent investment selection, excessive recordkeeping or management fees, concentration in employer stock — as well as benefit formulas applied incorrectly across a group and plan amendments that reduce benefits participants had already accrued.
Fiduciary breach claims have a structural feature that matters: under ERISA, losses to the plan are recovered for the plan itself, which is why these cases are so often brought on behalf of all participants rather than one. Kantor & Kantor has filed briefs with the United States Supreme Court on fiduciary duty and anti-cutback questions in this area. For individual disputes, see our page on retirement benefits claims.
Health Plan Coverage Denials
When a health plan denies a treatment by category rather than by patient, the denial is systemic by definition. We have pursued class claims over the blanket classification of proton beam therapy denials as experimental or investigational — a designation that is difficult to defend for treatments with an established clinical record, and one that is applied to every member who requests it, not evaluated case by case.
The same pattern appears with other categorical exclusions: specialty drug and step-therapy protocols, level-of-care rules that deny residential and intensive outpatient treatment as a matter of policy, and out-of-network reimbursement methodologies applied uniformly across a plan population.
Mental Health and Parity Cases
Federal parity law generally prohibits a group health plan from imposing stricter limits on mental health and substance use disorder benefits than it imposes on comparable medical and surgical benefits. Plans violate it in ways that are almost invisible to any single member — a stricter medical-necessity standard applied only to behavioral health, a review process with more hurdles, a limit that exists on one side of the plan and not the other.
We have pursued claims over plans that cover nutrition counseling for conditions like diabetes while denying it for eating disorder patients — a disparity that affects everyone in the plan with that diagnosis, not one person. Our work on eating disorder treatment denials runs alongside these cases.
Life Insurance and Accidental Death Cases
Group life and accidental death and dismemberment claims are denied in patterned ways: evidence-of-insurability requirements the employer never collected but the insurer relies on years later at the worst possible moment, lapse and conversion-notice failures, and exclusions read far more broadly than the policy language supports. When the same administrative failure runs through a plan, the beneficiaries affected by it share a claim.
Long-Term Disability Cases
Disability denials are usually individual, but not always. A reviewer protocol that systematically discounts self-reported symptoms, a definition of disability applied inconsistently at the 24-month change-of-definition point, or an offset calculation applied wrongly across a plan can all affect a defined group in the same way. Most of our long-term disability denials work is individual, and we will say so when that is the better route.
How an ERISA Class Action Works
- We investigate before we file. We read the plan documents, the denial letters, and the administrative record, and we look for evidence the conduct was applied to a group rather than to a person.
- A complaint is filed with named plaintiffs. One or more affected people serve as class representatives, bringing the case on behalf of everyone in the proposed class.
- We ask the court to certify the class. This is the pivotal moment. The judge decides whether the group is numerous enough that individual suits are impractical, whether the members share common questions, whether the representatives’ claims are typical of the group, and whether the representatives and their counsel will adequately protect everyone’s interests.
- Notice goes out — and what it says depends on the type of class. In a class certified for money damages, members are told they may opt out and pursue their own case; if they do nothing, they stay in and are bound by the outcome. But many ERISA cases — particularly fiduciary breach claims seeking relief for the plan, and cases seeking an order changing the plan’s conduct — are certified as mandatory classes with no opt-out right at all. Read any notice you receive carefully, because these are not the same thing.
- The case is litigated or resolved. Discovery, expert work, motions, and either trial or settlement. Any class settlement must be approved by the court as fair, reasonable, and adequate — the parties cannot simply agree to it privately.
What a Class Representative Actually Does
People are often reluctant to be a named plaintiff because they imagine it means running the case. It does not. The role is real but bounded.
A class representative brings a claim typical of the group and agrees to act in the group’s interest, not only their own — that is a genuine obligation, and occasionally it means supporting a resolution that is right for the class. In practice, the work is reviewing documents, sitting for a deposition, producing relevant records, staying informed, and staying in touch with your lawyers. Some travel is occasionally required.
You do not negotiate the settlement yourself, and you do not carry the cost. Courts may approve an additional service award for a class representative in recognition of the time contributed, but that is discretionary, it is not guaranteed, and in some courts it is restricted — so it should never be the reason someone takes the role.
Who Can Join a Class Action
If you were harmed by the same conduct as the rest of the class and you fall inside the class definition the court approves, you are generally a member — often without doing anything at all. Once a class is certified, notice is sent to the people the parties can identify, explaining the case and what your options are.
You do not have to wait for a notice to arrive. If you believe you were denied a benefit for a reason that probably applied to other people in your plan, contact us. Some of the strongest cases begin with one person noticing that their denial letter sounds like a form.
What You Can Recover
ERISA class actions produce three kinds of outcomes, often in combination.
- The benefits themselves. Payment of what was wrongly denied, or restoration of losses to the plan where the claim is for breach of fiduciary duty.
- A change in the plan’s conduct. A court order requiring the plan to stop a practice, reprocess a category of claims under a correct standard, or comply with its own terms. For many class members this is worth more than the money.
- Attorneys’ fees and costs, awarded by the court and paid separately from class recovery.
One important limit: ERISA does not permit extra-contractual damages. Emotional distress and punitive damages are not available, no matter how badly the plan behaved. It is a real constraint, and it is better to know it at the beginning than to learn it at the end.
What Does a Class Action Lawyer Cost?
Nothing up front. We handle class actions on a contingency basis: we advance the litigation costs, and legal fees are paid only out of a settlement or a favorable judgment. In a class case, the court reviews and approves those fees — a judge, not the law firm, decides what is reasonable. If there is no recovery, you owe us nothing.
The initial case evaluation is free, and it is a real evaluation. If we do not think you have a class claim, we will tell you that, and we will tell you what we think you do have.
Why Employees and Retirees Choose Kantor & Kantor
We do this work, not everything. Our practice is employee benefits and insurance denials under ERISA. That is not a marketing position — it is why we can look at a denial letter and recognize plan-wide conduct in it.
We litigate. Insurers know which firms will try a case and which will not. Our founding partner has been litigating benefits denials since 1986, and our attorneys have submitted briefs to the United States Supreme Court on ERISA questions including the anti-cutback rule and fiduciary duty.
We are candid about the route. Class actions are not always better than individual claims, and we will say so when an individual case would serve you better. A firm that only ever recommends the bigger case is not evaluating yours.
We treat clients like people. The plan treated you like a file number. We do not.
Class Action FAQ
What is an ERISA class action?
A lawsuit brought under the Employee Retirement Income Security Act on behalf of a group of plan participants or beneficiaries who were harmed by the same conduct — a coverage exclusion, a plan amendment, a fiduciary decision, or a claims practice applied across the plan rather than decided individually.
Do I have to pay anything to join a class action?
No. Class actions are handled on contingency. The firm advances costs, and fees are paid from any recovery and must be approved by the court. If there is no recovery, class members owe nothing.
Can I opt out of a class action?
It depends on how the class was certified. In classes certified for money damages, members are given the right to opt out and pursue an individual case. Many ERISA classes — especially fiduciary breach claims seeking relief for the plan and cases seeking to change plan conduct — are mandatory, with no opt-out right. The notice you receive will state which applies.
How long does a class action take?
Longer than an individual claim. Certification alone is often litigated for a year or more, and complex benefits cases can run several years. The tradeoff is that a class action can reach conduct an individual appeal never could.
Will I have to go to court?
Almost certainly not, unless you serve as a class representative — and even then, most of the work is document review and a deposition rather than testimony at trial. Ordinary class members typically do nothing beyond responding to a notice.
My denial seems individual. Should I still call?
Yes. Most systemic denials look individual to the person receiving them — that is precisely why they persist. We handle individual benefits claims as well, so the conversation is worth having either way.
Talk to Our Class Action Attorneys
If your benefits were denied for a reason that sounds like policy rather than a decision about you, we would like to hear about it. The case evaluation is free, there is no obligation, and if what you have is an individual claim rather than a class claim, we will tell you that plainly.
Contact us today or call Kantor & Kantor at 866-318-5283 to request a free case evaluation. We are people helping people, and we are ready to fight for you.
Denied benefits that hit your whole plan? Contact Kantor & Kantor, LLP online or call us at 866-318-5283 to discuss how we may be able to help.
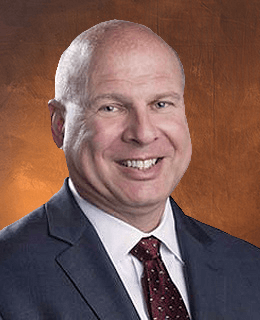
Attorney Glenn R. Kantor
Glenn Kantor is a founding partner of Kantor & Kantor LLP. As a young attorney, Glenn saw the injustice of wrongful insurance denials and created a law firm to represent individuals seeking to obtain their rightful benefits. Glenn is committed to ensure that clients receive the benefits they are entitled to under their insurance policies or group health plans. [Attorney Bio]