Seattle sits between two insurance realities that rarely surface until a claim gets denied: the promise printed on the declarations page, and the claims process that decides whether that promise is honored. A long-term disability claim gets denied after years of premiums. A benefit governed by ERISA, the federal law covering most employer-sponsored plans, gets terminated in a letter that explains very little. A homeowner’s claim gets denied on the reasoning that the damage predated the policy period.
Kantor & Kantor LLP built a practice around that gap. For decades, our attorneys have represented policyholders in disputes with insurers over denied disability, life, health, and property claims. We are people helping people, and that phrase shapes how we take on cases rather than serving as a slogan. If an insurer has denied your claim, our Seattle insurance attorneys can review what happened and explain, honestly, whether the conduct crosses into bad faith under Washington law. Call us at 818-886-2525 when you are ready to talk it through, and there is no obligation attached to that conversation.

Was your insurance claim denied in Seattle? Contact Kantor & Kantor, LLP online or call us at 818-886-2525 for a free case evaluation.
Key Takeaways: Seattle Insurance Bad Faith
- Not every denied claim amounts to bad faith. Washington law requires the insurer’s conduct to be unreasonable, frivolous, or unfounded before it qualifies.
- Washington’s Insurance Fair Conduct Act allows policyholders to sue directly for unreasonable denial and can result in treble damages and attorney fees.
- Most employer-sponsored disability, life, and health coverage is governed by ERISA, which preempts state bad faith remedies entirely.
- Whether a policy came through an employer or was purchased individually changes the deadline, the evidence rules, and what a successful claim is worth.
- Washington prohibits discretionary clauses in disability insurance policies, meaning courts weigh the evidence independently rather than deferring to the insurer.
What Counts as Insurance Bad Faith in Washington?
Insurance bad faith in Washington is conduct that goes beyond a reasonable coverage decision and instead reflects an insurer placing its own financial interest above its contractual duty to the policyholder. Not every denied claim amounts to bad faith. Insurance companies deny claims for legitimate reasons that hold up under scrutiny: a policy exclusion applies, documentation is missing, or a deadline has passed unmet. Under the common law standard, the insurer’s conduct must be unreasonable, frivolous, or unfounded before it qualifies.
Recognizing that difference on a first read is not always easy, which is part of why so many denials go unchallenged. Washington law recognizes that an insurer owes its policyholder a duty of good faith, separate from the terms written into the policy itself.
When an insurer investigates a claim unfairly, misrepresents policy language, or refuses to explain a denial in understandable terms, that conduct may cross into bad faith. Our attorneys evaluate what counts as insurance bad faith by examining claim files, correspondence, and the reasoning an insurer gave, or failed to give, for its decision. That review is a factual exercise rather than a judgment about motive.
A person searching for a denied insurance claim lawyer in Seattle has often already spent months on phone calls and read a denial letter that raised more questions than it answered. None of that means the policyholder did anything wrong. A Seattle bad faith insurance lawyer looks at that same file with a different question in mind: not whether the outcome was unwelcome, but whether the insurer’s conduct met the standard Washington law requires.

Why Washington Law Treats Insurance Denials Differently
Washington is one of a smaller number of states that gives policyholders a direct path to sue an insurer for unreasonable denial of a claim, separate from any breach of contract claim. The Insurance Fair Conduct Act, codified at RCW 48.30.015, allows a first-party claimant who is unreasonably denied a claim for coverage or payment of benefits to bring an action in superior court. A court may increase the award to an amount not exceeding three times the actual damages, and it must award reasonable attorney fees and litigation costs to a claimant who prevails.
The reach of that right is narrower than it first appears. The Washington Supreme Court has held that a violation of the claims-handling regulations, standing alone, does not support an action under the statute, because an unreasonable denial of coverage or benefits is what the statute requires. The statute also requires written notice of the basis for the action, sent to both the insurer and the Office of the Insurance Commissioner, 20 days before a lawsuit is filed, and the limitations period is tolled during that window.
Washington’s administrative code sets standards for how insurers must handle claims as well. WAC 284-30-330 lists claims-handling practices considered unfair, including failing to respond to communications, failing to adopt reasonable standards for prompt investigation, and failing to give a reasonable explanation for a denial. The state’s Consumer Protection Act gives policyholders another avenue when an insurer’s conduct amounts to an unfair or deceptive practice affecting the public interest.
Washington also closed off a policy provision that once made disability denials much harder to challenge. WAC 284-96-012 prohibits discretionary clauses in disability insurance policies, which means an insurer cannot write into the policy that its own reading of the terms binds a court. Without that clause, a reviewing court weighs the evidence for itself rather than deferring to the insurer’s conclusion.
An insurer operating in Seattle is not answerable only to the policyholder in front of it, either. The Washington State Office of the Insurance Commissioner oversees how carriers conduct business statewide, and a pattern of denials can draw regulatory attention on top of a private lawsuit. Filing a complaint with that office and pursuing a private claim are not mutually exclusive, and many Seattle policyholders do both.
Does Your Coverage Come Through an Employer?
Whether a policy came through your job usually decides which of these remedies is available to you at all. Most group disability, life, and health coverage offered through a private employer is governed by ERISA, a federal law that replaces state remedies with a claim and appeal process of its own. Where ERISA applies, the United States Supreme Court has held that state bad faith and extracontractual remedies are preempted, so there is no Insurance Fair Conduct Act claim, no Consumer Protection Act claim, and no award of triple damages.
What ERISA provides instead is a mandatory internal appeal, followed by a suit in federal court to recover the benefits the plan owes. The record built during that appeal is often the only record a federal judge will ever see, which makes it far more consequential than most people are told at the time. Appeal deadlines are short, and they run from the date of the denial letter.
Coverage outside ERISA keeps the full range of Washington remedies. Policies bought individually, church plans, government employee plans, and short-term disability paid out of an employer’s own general funds all sit outside the federal scheme. Telling the two apart from the policy documents is the first thing our attorneys look at, because the answer changes the deadline, the evidence rules, and what a successful claim is worth.

The Claims We See Denied Across Seattle and the Puget Sound
Seattle’s economy shapes the kinds of claims that end up in front of us. A workforce built around technology, aviation, healthcare, and maritime industries files an unusually high volume of long-term and short-term disability claims, most of them governed by ERISA because the coverage comes through an employer-sponsored plan. When an insurer terminates disability and ERISA benefit claims, the review usually happens on paper, conducted by a claims examiner who has never met the person filing.
Life insurance denials follow their own pattern. Beneficiaries in Seattle contact us after an insurer rescinds a policy, meaning it cancels the coverage retroactively and returns the premiums, citing an application question the insured supposedly answered incorrectly. These cases often move quickly once litigation begins, since the underwriting file either supports the rescission or it does not.
Homeowner’s insurance claims carry a distinctly regional flavor here. Puget Sound windstorms, heavy winter rainfall, and wildfire smoke drifting in from eastern Washington and Canada all generate claims that turn on questions of cause, timing, and policy wording. A roof damaged in one winter and a house filled with smoke odor the following summer can both end with adjusters and policyholders reading the same policy language differently, which is where a documented, well-supported claim makes the biggest difference.
Long-term care claims, retirement benefit disputes, and denied prescription or treatment claims round out the areas where Washington policyholders most often need an advocate who understands both the claim record and the insurance code. Chemotherapy, radiation, and surgery denials share a common shape as claim categories, in that a recommended course of care is declined on paper review. Retirement and pension disputes turn on plan documents and actuarial calculations rather than medical evidence.
How Do Our Seattle Insurance Attorneys Build a Case?
Every case begins with the claim file. Our Seattle insurance attorneys request the complete administrative record from the insurer, including internal notes, medical reviews, and every communication exchanged during the claims process. That record usually tells a more complete story than the denial letter alone, and it often shows where the insurer’s reasoning broke down.
From there, the approach depends on the claim. An ERISA long-term disability denial calls for strengthening the administrative record before the internal appeal closes, since courts reviewing ERISA claims frequently limit their review to what already exists in the file. A homeowner’s bad-faith claim may call for an independent damage assessment, and a life insurance rescission for records showing the insured answered application questions honestly.
None of these approaches is interchangeable, and applying the wrong one can cost a policyholder months they do not have to spare. Our attorneys prepare every Seattle case on the assumption that it may need to go before a judge, while working toward a resolution that does not require one.
What Our Firm Is Built Around
Kantor & Kantor LLP has spent decades on one side of the insurance relationship: the policyholder’s side. That focus, rather than a general litigation practice picking up insurance cases occasionally, shapes how our attorneys read a claim file, negotiate with adjusters, and prepare for trial when negotiation does not resolve a claim fairly.
We serve Seattle and King County from our office in Gig Harbor, and our attorneys bring national experience litigating ERISA, disability, and insurance bad faith claims into every Washington case. That combination matters because ERISA claims are litigated in federal court under a body of law that does not change at the state line, while the claims that survive outside ERISA are governed entirely by Washington authority. Every client relationship starts with an honest conversation about the claim, not a scripted intake built to sign a case regardless of merit.
Some claims genuinely do not amount to bad faith, and we will tell a prospective client that directly rather than pursue a case built on hope instead of evidence. That candor shapes every recommendation our attorneys make, from the first phone call through settlement or trial.
Seattle Insurance Bad Faith FAQs
These are the questions Seattle policyholders ask us most often after a claim has been denied.
Does hiring a Seattle insurance attorney slow down or speed up a claim?
Involving an attorney does not add a required step to the claims process. What an attorney mainly changes is what goes into the record, which matters most on an ERISA claim, where the internal appeal is usually the last chance to add evidence.
What evidence matters most in proving bad faith beyond the claim file itself?
Internal claims-handling manuals, prior complaints filed against the same insurer with the state regulator, independent medical or engineering opinions that contradict the insurer’s reviewer, and any record showing the insurer ignored evidence the policyholder submitted all carry weight beyond the file alone. Timelines matter too, since long unexplained gaps often say as much as the correspondence itself.
Can a policyholder still pursue a bad faith claim after accepting a partial payment?
Often, yes. Accepting a partial payment does not automatically waive the right to challenge how the remainder of the claim was handled, though the policy language and any release signed at the time should be reviewed carefully first.
Do out-of-state insurers licensed in Washington have to follow the same bad faith standards?
Yes, for the policies Washington law reaches. An insurer authorized to sell policies in Washington must follow the state’s claims-handling regulations regardless of where the company itself is headquartered. The limit is not geography but the kind of plan, because coverage governed by ERISA answers to federal law instead.
Is there a cost to have an attorney review a denied claim?
Our firm reviews denied insurance and ERISA claims without charging a fee for that initial conversation. We explain in writing how fees and case costs are handled before you decide whether to move forward.
What is the difference between a breach of contract claim and a bad faith claim?
A breach of contract claim asks whether the insurer owed money under the policy and failed to pay it. A bad faith claim asks how the insurer behaved while deciding, and it can reach treble damages, meaning an award a court may increase to as much as three times the actual loss. The two can be brought together wherever state law governs the policy.
Do wildfire smoke damage claims qualify for bad faith review in Washington?
They can, depending on how the insurer investigated and responded. Wildfire smoke damage to homes and belongings is a newer category of claim in the Pacific Northwest, and insurers do not always apply consistent standards when evaluating it.
Talk With Us About What Happened With Your Claim
A denial letter is a decision, not the end of the process. Understanding which set of rules governs your policy is usually the first step toward knowing whether that decision holds up.
Kantor & Kantor LLP has represented policyholders in Washington and nationwide in disputes over denied disability and ERISA benefit claims, life insurance rescissions, homeowner’s claims, and long-term care denials. We are people helping people, and there is no obligation attached to a conversation with our attorneys. Contact us today or call 818-886-2525 to discuss your options, at whatever pace makes sense for you.
A denial letter is not the end of the process. Contact Kantor & Kantor, LLP online or call us at 818-886-2525 to discuss how we may be able to help you challenge the decision and secure the benefits you deserve.
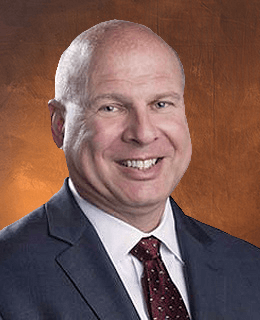
Attorney Glenn R. Kantor
Glenn Kantor is a founding partner of Kantor & Kantor LLP. As a young attorney, Glenn saw the injustice of wrongful insurance denials and created a law firm to represent individuals seeking to obtain their rightful benefits. Glenn is committed to ensure that clients receive the benefits they are entitled to under their insurance policies or group health plans. [Attorney Bio]